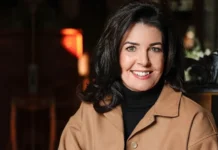
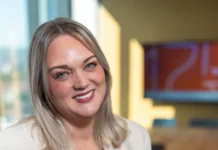

The Commercial Mortgage-Backed Securities (CMBS) market is now a $1.8 trillion financial pillar underpinning vast swaths of the United States’ commercial real estate sector. Yet, it remains opaque to everyday investors and restricted to institutional players with deep pockets. As this complex market has transformed over three decades, from early experimental structures to sophisticated, investor-grade instruments, one seasoned figure has evolved alongside it. Edward L. Shugrue III, Managing Director at RiverPark Funds, stands out for his enduring influence on the architecture of CMBS, shaping and adapting to its every iteration.
Having joined a leading American investment bank, securities trading, and brokerage firm in 1988, Shugrue was present at CMBS’s conception. “We were doing large, private credit transactions that were effectively CMBS, though we didn’t call it that yet,” he explains.
CMBS emerged in response to a crisis, specifically the collapse of the savings and loan industry and the rise in real estate delinquencies that followed. It began as a way for banks to offload troubled commercial real estate loans onto the broader capital markets and slowly gained traction. However, quality control was nearly nonexistent at first. “In the early days, it was just about filling a box,” Shugrue recalls. “Anything went: land, nursing homes, and other assets that never should’ve been included.”
Later, as a board member of a trade association for the commercial real estate finance industry, Shugrue helped formalize CMBS standards. He aimed to include only income-producing properties and intended to establish underwriting consistency.
The CMBS landscape has evolved since then. Rated by major credit agencies and widely traded by major banks, CMBS instruments primarily consist of commercial first mortgage loans secured by income-producing properties. These could include industrial parks, multifamily apartments, and high-end retail and hospitality assets.
Today, the CMBS market is made up of two different collateral packages: conduit loans and single-asset, single-borrower (SASB) loans. “Conduit loans are usually built from hundreds of smaller loans bundled into a billion-dollar-plus pool. SASB, on the other hand, consists of larger, institutional quality assets,” Shugrue explains.
However, as the industry expert has observed, conduit deals have struggled over time. According to data from Trepp, serious delinquencies in conduit CMBS rose to nearly 6% in 2024. This figure far exceeds historical averages and points to systemic weaknesses, particularly in the office and retail segments.
On the contrary, SASB deals have gained ground. It now accounts for the majority of CMBS issuance, reflecting investor appetite for greater transparency and institutional sponsor quality. These transactions typically consist of a single high-profile property or a large, diversified portfolio owned by a single borrower, typically in the billions.
“SASB gives you better transparency,” says Shugrue. “You can analyze the entire credit stack, cash flows, leases, and know exactly what you’re investing in.” It’s also where the RiverPark Floating Rate CMBS Fund makes the majority of its investments, and has done so for over a decade.
Founded in 2010 and internalized at RiverPark in 2018, the fund aims to provide individual investors access to an asset class traditionally reserved for institutional giants. “There are very few publicly traded CMBS funds in the US, particularly that have the multi-year track record that we have,” Shugrue states. The fund targets Investment-Grade tranches of SASB deals with a heavy emphasis on industrial and multifamily assets, representing the vast majority of its portfolio.
The fund also offers daily liquidity, another key innovation. “Most CMBS investments come with high fees and long lockups with private funds managed by institutional firms,” Shugrue explains. “We offer the same access but with full transparency and relatively low pricing.”
Essentially, the RiverPark Floating Rate CMBS Fund brings a traditionally private capital structure to individual investors. “For this $1.8 trillion market, we created a vehicle that gives individual investors access to institutional-grade assets without the institutional barriers,” Shugrue says.
As its Portfolio Manager, Shugrue’s multi-dimensional experience has been pivotal in the RiverPark Floating Rate CMBS Fund’s creation. He’s been a lender, an investor, a special servicer, and an architect of the market itself. After co-building one of the first real estate mezzanine platforms at a premier American real estate investment trust, he ran his private funds and restructured distressed assets during the Global Financial Crisis.
This experience influences his investment decisions. “For example, we were an aggressive buyer of luxury AAA hotel bonds during COVID, when many others were sellers,” Shugrue shares. “We purchased these tranches of top hotel properties at significant discounts that were later repaid at par.” Shugrue recognizes that the fund’s investment strategy is dynamic, and that today, for example, the fund owns no hotel assets. Such a contrarian but informed strategy reflects profound market intuition and long memory.
The CMBS market will continue to shift, driven by macroeconomic changes, interest rates, credit quality, and investor demand. Edward Shugrue remains at the center, balancing innovation with discipline. “I’ve seen the CMBS market develop significantly over 30 years with an ever-improving emphasis on credit quality and transparency,” he reflects. “I helped shape that evolution. And now, our fund allows individual investors to access this otherwise private market.”